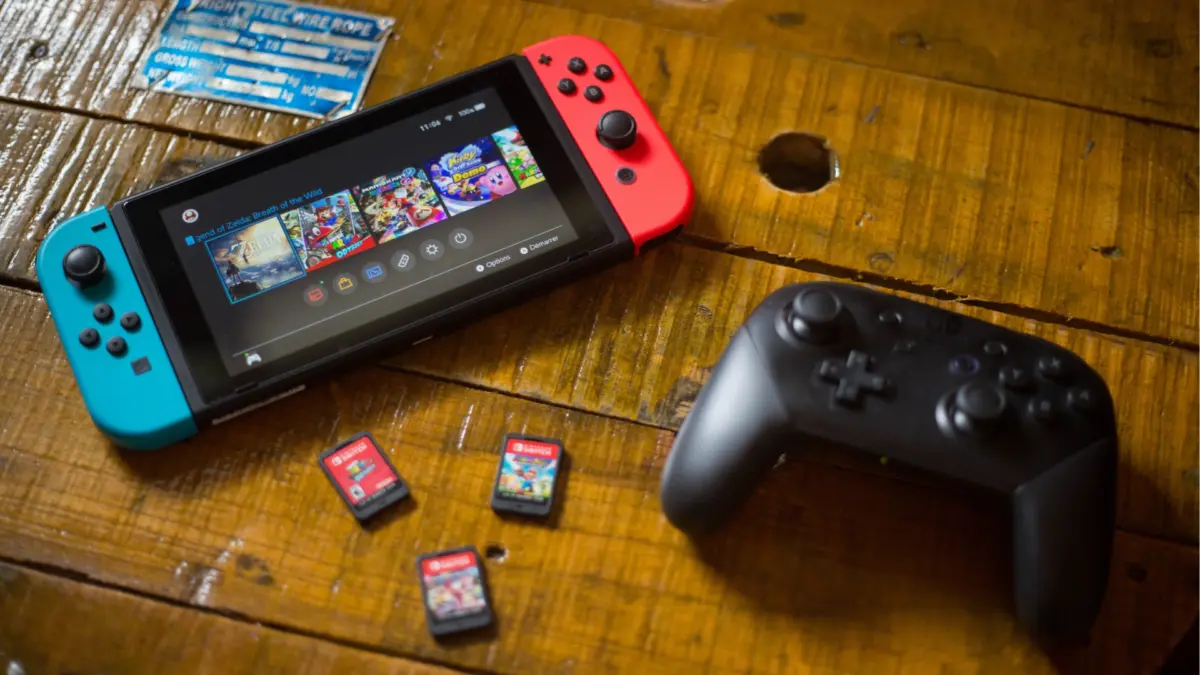
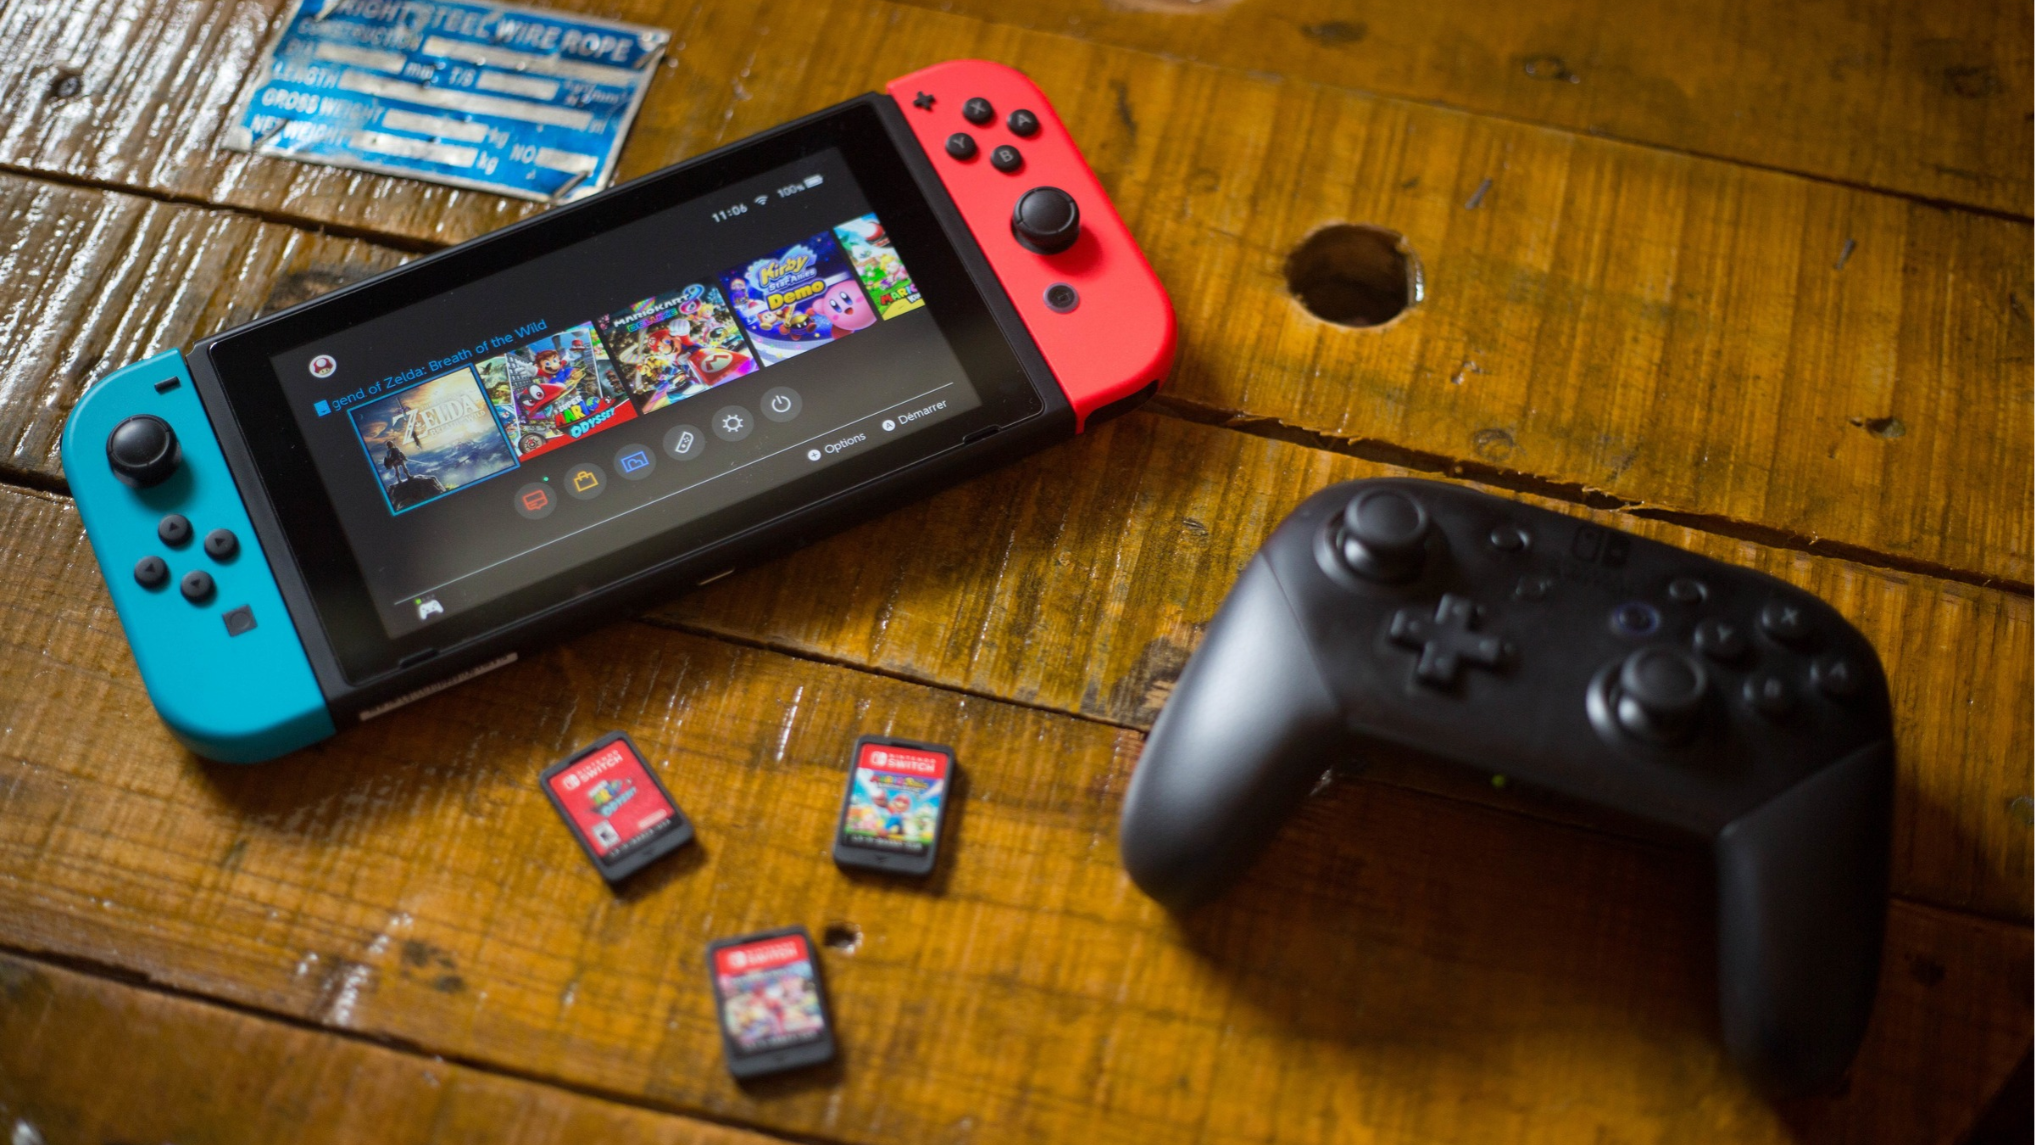
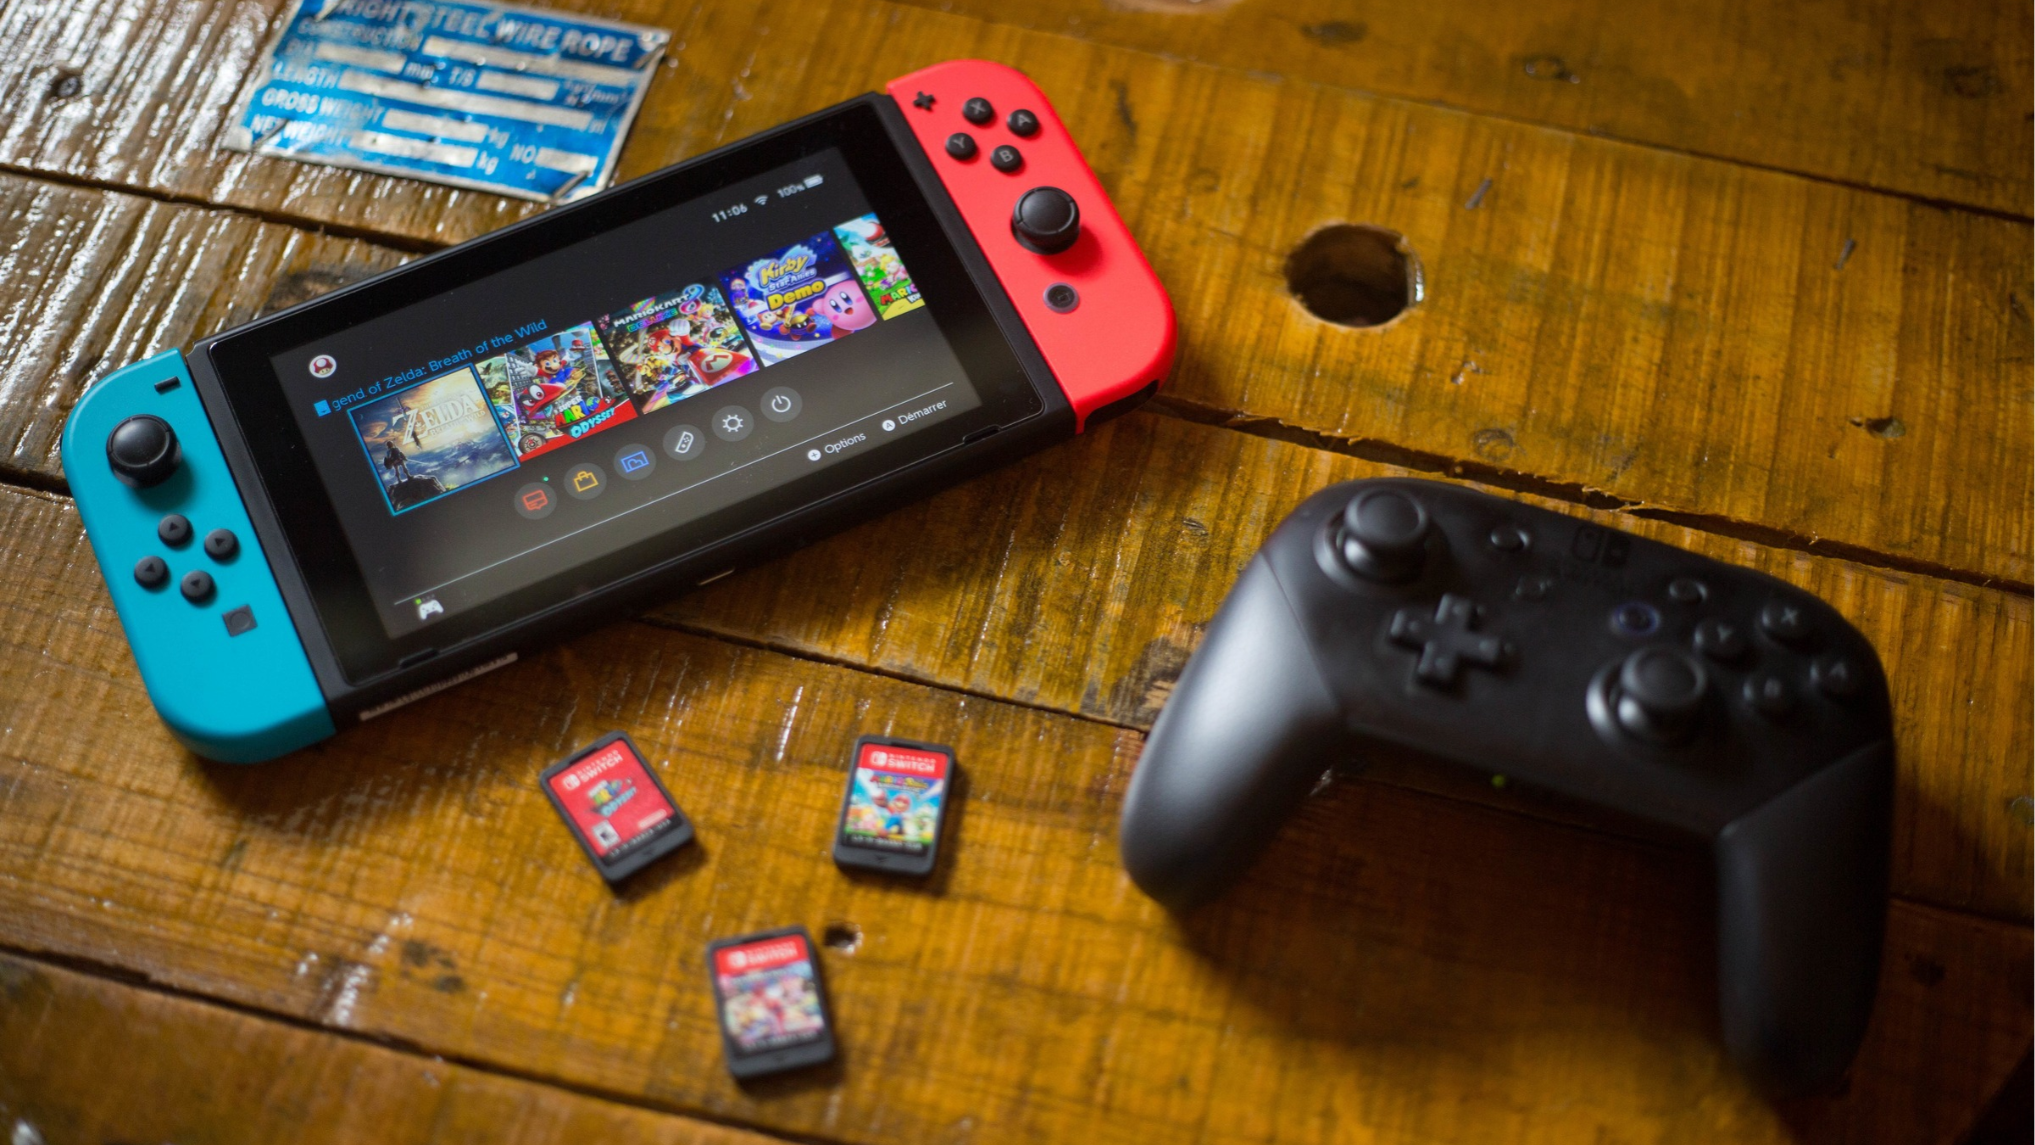
For years, Macronix has served as a foundational partner for Nintendo, providing the specialized Read-Only Memory (ROM) chips utilized inside game cartridges for both the immensely popular Nintendo Switch and its highly anticipated, yet-to-be-detailed successor, widely referred to in the industry as the Switch 2. Because these cartridges rely entirely on custom ROM technology to store and rapidly read game data without the installation times typical of optical discs, any disruption to this supply chain carries major implications for how physical games are produced, distributed, and priced.
The timing of this reported business shift comes at a delicate juncture for the gaming ecosystem. Storage technology across the tech sector is already becoming increasingly expensive, driven by surging global demand for AI infrastructure, enterprise cloud storage, and high-performance server components. Semiconductor foundries are frequently forced to reallocate wafer capacity to the most profitable sectors. With data center operators willing to pay top dollar for advanced NAND and NOR flash chips to support the relentless expansion of cloud computing and artificial intelligence, component makers are finding legacy markets, such as console ROM production, increasingly
difficult to justify from a margin perspective.
This strategic retreat by a primary supplier introduces a cascade of challenges for Nintendo as it plans hardware lifecycles and software distribution strategies for the current generation and beyond. Game cartridges are notoriously more expensive to manufacture than standard optical discs or digital distribution keys, primarily due to the raw material costs of the silicon chips embedded inside them. If Macronix winds down its ROM business and Nintendo is forced to secure alternative manufacturing partners, the reduced competition and tightened foundry capacity could drive up the per-unit cost of producing physical game cartridges significantly.
Faced with rising manufacturing costs, Nintendo will likely have to weigh a series of difficult options that could permanently alter the consumer experience. One immediate possibility is that the company, or third-party publishers releasing games for its platforms, may pass those increased production expenses directly onto consumers by raising the retail price of physical game cartridges. While standard video game prices have already seen upward pressure across the industry in recent years, higher cartridge production overhead could widen the price gap between physical and digital editions even further.
Alternatively, publishers might lean more heavily into alternative physical formats, such as Game-Key cards or boxes that contain download codes rather than complete software data. While these hybrid products reduce manufacturing costs by substituting a traditional ROM cartridge for a piece of cardboard or plastic with a digital redemption code, they have historically faced pushback from collectors and purists who value the preservation aspect of owning a complete game on physical media. The proliferation of Game-Key solutions essentially bridges the gap between physical retail shelves and purely digital ecosystems, but it accelerates the departure from the traditional plug-and-play cartridge model that has defined handheld and console gaming for decades.
Beyond these alternatives, the shrinking availability and rising cost of dedicated ROM manufacturing could simply accelerate the industry-wide transition toward digital-only purchases. Digital distribution eliminates the physical supply chain entirely, bypassing raw material constraints, shipping logistics, and manufacturing bottlenecks. For hardware manufacturers, digital sales also offer higher profit margins by removing retailers and physical production from the equation. However, a forced march toward a fully digital marketplace brings its own set of consumer concerns, including the eventual loss of digital storefronts, the inability to trade or resell used games, and long-term preservation challenges when servers are eventually shut down.
As the industry digests the implications of Macronix’s reported pivot away from ROM chips, the broader trajectory of physical media appears increasingly precarious. While Nintendo has historically championed physical formats alongside digital storefronts—maintaining a vibrant market for cartridges even as Sony and Microsoft largely transitioned their console ecosystems to optical discs and downloadable files—the economic realities of semiconductor manufacturing may force its hand. Whether through higher retail prices, alternative physical distribution methods, or a decisive push toward the Nintendo eShop, the shifting priorities of microchip suppliers are bringing the traditional era of physical game cartridges one step closer to its twilight.