The limited partners who provide the capital to venture firms—often described as the "money behind the money"—are experiencing a remarkably unique market environment. Standing at the intersection of unprecedented artificial intelligence valuations and shifting private equity conventions, these institutional investors find themselves in uncharted yet potentially exceedingly lucrative territory.
Normally, limited partners, or LPs, follow a well-established playbook. They spread their bets across a diverse array of firms to construct resilient portfolios, writing checks to both emerging managers and established institutions, as well as generalists and specialists alike. The overarching goal has always been to secure strong returns while rigorously minimizing risk.
However, in the current landscape, that typical playbook has been thrown entirely out the window. The valuations of dominant artificial intelligence players like OpenAI and Anthropic have shot up so quickly that nearly every venture capital firm has piled into the exact same companies on their way up. This trend frequently plays out within the same venture portfolios, directly defying the longstanding venture convention of avoiding conflicting investments.
Yet, remarkably, no one is complaining. The LPs currently navigating this environment remain unbothered by these concentrated, high-stakes gambles, given the massive potential returns on the horizon; instead, they are anticipating a financial bonanza. Even so, these institutional backers acknowledge that danger lies ahead, describing the current market climate as a "yellow light" situation. They are growing increasingly uneasy about the accelerating speed at which venture capitalists are returning to the market to raise fresh funds.
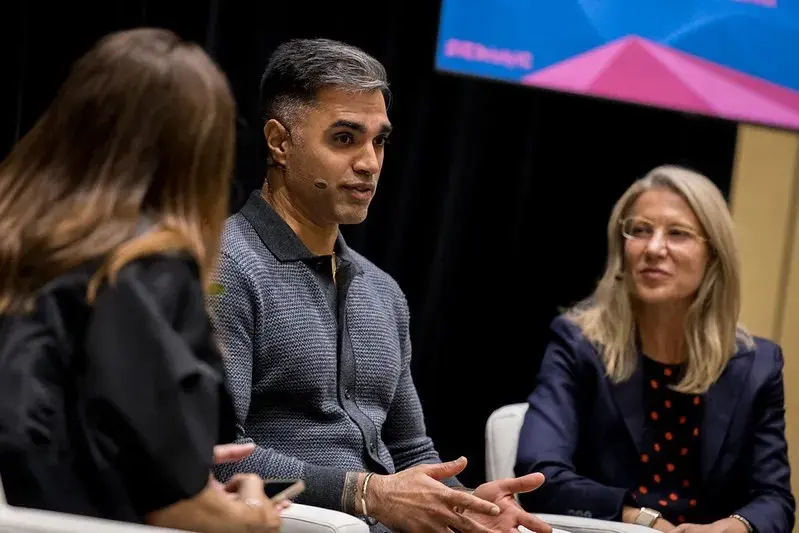
To examine these strange days of high excitement and underlying anxiety, industry leaders Beezer Clarkson of LGT Capital Partners, a Zurich-based diversified asset manager, and Amit Bhatti of TrueBridge, a Chapel Hill firm that focuses exclusively on venture capital, recently sat down to discuss the evolving state of the startup ecosystem.
Navigating Chaos and Excitement in Venture Capital
These are undoubtedly strange times for the private markets—a period marked by intense excitement mixed with underlying caution. When examining their evolving roles and overall place in the modern startup ecosystem, veteran investors see more opportunity than alarm.
Beezer Clarkson notes that while the schedule is exceptionally demanding, the environment is far from frightening. With a career spanning a couple of decades, Clarkson has witnessed numerous market cycles, which helps mitigate fear and instills a deep appreciation for the natural rhythms of venture capital. Recognizing that market ups and downs are inevitable, Clarkson emphasizes the importance of enjoying the upside periods, noting that the positive phases are far more enjoyable than the inevitable downturns.
Amit Bhatti shares a similarly optimistic perspective, viewing the current climate as an exciting moment for the asset class. While venture capital is sometimes viewed as a niche sector, the all-consuming rise of artificial intelligence has thrust the entire industry into the global spotlight. With all eyes focused squarely on this corner of private equity, Bhatti views the current pace of investing and shifting valuations not as a crisis, but as a sign that deeply meaningful developments are taking place.
The Power Law of AI Concentration and Fund Portfolios
One of the most striking anomalies of the current cycle is how venture funds that are meant to maintain institutional diversification now hold identical brand-name assets. Multiple funds backed by the same LPs all hold stakes in OpenAI and Anthropic, multiplied across countless individual portfolios.
Addressing how this concentration impacts portfolio strategy, Amit Bhatti points out that venture capital has always fundamentally operated as a power law business. Consequently, portfolio concentration is viewed as a positive feature rather than a bug. As older venture funds reach maturity, their holdings naturally consolidate into a select few dominant names. Historical vintages often feature heavy concentrations in market-defining companies like Databricks, SpaceX, and Stripe. For the current generation of funds, seeing substantial exposure to Anthropic and OpenAI aligns with historical norms, even if the speed of this consolidation is entirely unprecedented. Not every company will succeed, but consolidation remains a natural part of the venture lifecycle.
From an early-stage perspective, Beezer Clarkson observes that the opportunity set remains remarkably diverse, with smaller check sizes deployed across a wider variety of targets. While these early-stage bets ultimately aggregate into the same massive late-stage companies, early-stage funds avoid the giant late-stage rounds, preserving a higher degree of portfolio diversity.
The Acceleration of Fund Pacing and Warning Signs
Historically, venture funds operated on reliable four-year investment cycles. Over recent years, however, that pacing has compressed dramatically, shrinking down to three years, two years, and in some cases, a blistering 18 or even 12 months.
This accelerated deployment has sparked important conversations among LPs regarding market sustainability. Clarkson points out that seeing funds return on a one-year pacing schedule is exceptionally fast compared to the historical norm of two to two-and-a-half years. Managers deploying capital this rapidly are typically writing large, concentrated checks, which can serve as a worrisome sign. While such a strategy might ultimately succeed, constructing a successful portfolio out of one-year vintages is historically much more difficult.
Echoing these concerns, Bhatti notes that while a 24- to 36-month window was once considered normal, a 12- to 18-month cycle has become common for fast-moving managers. Furthermore, many funds are bumping up their fund sizes mid-cycle—a decidedly unusual practice driven largely by the sheer scale of modern financing rounds. When a company like Anthropic raises a massive quantum of capital and a fund commits 20% of its capital to the round, its deployment pacing inevitably accelerates. Additionally, with seed round sizes nearly doubling, lead investors must write checks twice as large, creating what Bhatti describes as a classic "yellow light" scenario that produces some institutional heartburn.
Despite the rapid pacing, underlying fundamentals tell a different story than past speculative bubbles. Unlike previous periods of accelerated investment characterized by zero-revenue crypto ventures, today’s market features companies rapidly scaling from zero to $100 million in revenue at an unprecedented pace.
Managing LP Commitments and Capital Constraints
When a top-tier manager returns to the market every year to raise a new fund while previous returns remain locked up on paper as unrealized gains, institutional investors face difficult strategic decisions. LPs must carefully weigh whether to maintain their allocations or risk losing their coveted seats at the table.
According to Clarkson, walking away from a high-performing manager and attempting to return later is exceptionally difficult. While it occasionally happens, the more common industry practice is to downsize check sizes. During peak market frenzies, such as in 2021, many LPs halved their intended commitments to stretch capital across compressed timelines. Managing overall cash flow requires institutional investors to align fund pacing across their entire portfolios.
Bhatti explains that TrueBridge maintains a detailed calendar of anticipated capital commitments to ensure liquidity remains available when needed. Rather than sitting out entirely—which risks establishing a reputation as unreliable capital—investors often downsize or communicate allocation adjustments proactively. This capital dynamic also explains why venture managers frequently upsize existing vehicles rather than launching entirely new funds prematurely.
At the same time, the relentless pace of capital calls without corresponding distributions places significant operational strain on institutional LPs, such as university endowments, hospitals, and charitable foundations, which must balance ongoing operational commitments against locked-up venture capital.
The Evolution of Secondary Markets and Liquidity Options
As the venture ecosystem matures, the role of secondary markets has undergone a radical transformation, providing critical relief for funds seeking liquidity without waiting decades for an initial public offering.
Clarkson highlights that secondaries have become vastly more sophisticated over the last five years. While secondaries remain localized to the top tier of companies, their widespread prevalence is a net positive for the ecosystem, providing necessary alternatives to the traditional, decades-long wait for an IPO. Furthermore, secondary transactions now occur at multiple levels, with LPs selling stakes in general partners or strips of their portfolios as historical stigmas continue to fade.
Bhatti characterizes secondaries as the emerging third leg of venture liquidity, joining traditional IPOs and mergers and acquisitions. While private equity has long maintained a well-developed secondary market, venture capital historically viewed selling as a sign of financial distress. However, after managers experienced liquidity crunches following the 2021 market peak, attitudes shifted significantly. Today, managers utilize secondaries judiciously; while they rarely exit power law companies entirely, selling a modest portion of a position to return an entire fund represents a prudent strategy.
Concurrently, employee tenders and founder liquidity events have become prominent topics of discussion. While early employee liquidity can sometimes mirror the pitfalls of token-based crypto models where participants cash out and lose motivation, structured secondary tenders for mature, revenue-generating giants like Stripe and Databricks are viewed as entirely reasonable. Lead investors increasingly play an active governance role behind the scenes, advising companies on the appropriate timing for employee liquidity based on market leverage and financial maturity.
Ecosystem Evolution, Talent, and Geographic Hubs
As successful startups eventually go public and employees achieve financial liquidity, a new wave of capital and talent is recirculated back into the ecosystem. Historically, successful exits produce a fresh generation of angel investors, startup founders, and emerging venture capitalists—a phenomenon witnessed during the rise of Google and anticipated as artificial intelligence leaders mature.
While skyrocketing housing costs in San Francisco present economic hurdles for incoming talent, the deep concentration of technical expertise, networks, and institutional knowledge ensures that the Bay Area will likely remain the premier epicenter of technological innovation for the foreseeable future, even as satellite hubs continue to thrive in places like New York and suburban technology corridors.
The Landscape for Emerging Managers
Despite a market environment where a handful of massive venture funds secure the vast majority of institutional capital, opportunities for emerging managers persist. Clarkson notes that first-time and emerging managers raising funds one through three continue to secure backing, provided they present a highly differentiated point of view and a clear reason for existence. While fundraising has grown undeniably more challenging, smaller fund sizes—such as vehicles ranging from $25 million to $50 million—allow agile managers to successfully aggregate capital.
Bhatti adds that many successful investors begin with lean funds of $5 million or $10 million, formalizing their angel investment activities to build a verifiable track record of access and investment judgment. Attempting to raise a massive institutional fund on day one creates an unnecessary hurdle, whereas proving out a thesis early on paves the way for scalable future growth.
Ultimately, whether backing operator-turned-investor micro-funds or supporting young general partners embedded directly within elite academic networks at institutions like MIT, Harvard, and Stanford, institutional investors maintain flexible strategies. By writing targeted checks ranging from $3 million to $5 million while carefully monitoring fund concentration limits, LPs continue to fuel the next generation of venture capital innovation.