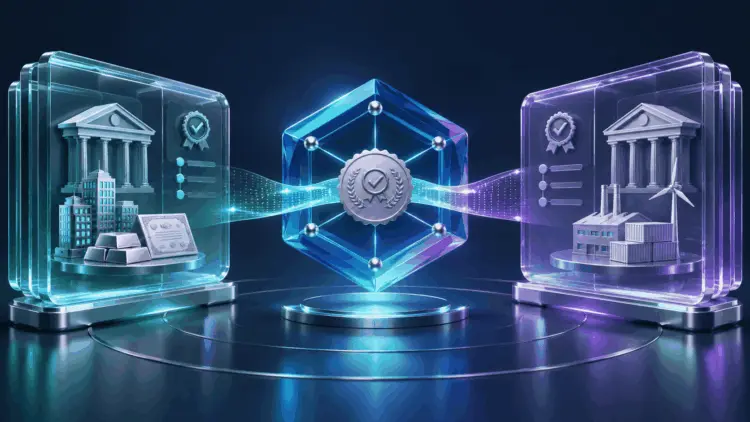
The intersection of traditional financial analysis and decentralized ledger technology reached a notable milestone recently, as Chainlink and Moody’s Ratings announced the successful completion of a collaborative cross-chain distribution pilot. Utilizing Chainlink’s Cross-Chain Interoperability Protocol, commonly known as CCIP, the initiative demonstrated how credit insights could be efficiently transmitted across multiple blockchain networks using representative test data.
The successful trial addresses a fundamental friction point within the rapidly evolving sector of tokenized finance: the critical need for financial information to travel seamlessly alongside digital assets. As tokenized financial instruments—such as bonds, real estate funds, and debt obligations—gain traction across diverse blockchain ecosystems, investors require consistent, up-to-date information regardless of which network hosts the underlying asset.
By connecting Moody’s proprietary Token Integration Engine, or TIE, with advanced cross-chain messaging architecture, the recent pilot showcased a potential blueprint for bridging traditional financial data pipelines with decentralized environments. However, while the technical demonstration marks a significant proof of concept, both organizations structured the exercise within strictly controlled parameters to evaluate operational capabilities without altering live production workflows.
A Ratings-Distribution Test with Defined Limits
To ensure operational security and maintain regulatory compliance, the pilot was conducted exclusively within a controlled testnet environment. The exercise spanned both permissioned and permissionless blockchain networks, utilizing representative data rather than live market information. Crucially, no actual rating actions were published onchain during the trial, and Moody’s existing, live dissemination processes remained entirely unaffected by the test.
This deliberate scope rendered the exercise exceptionally useful as a targeted interoperability test. By isolating the experiment from live production systems, the participating teams could thoroughly evaluate how well messaging infrastructure handles multi-chain data distribution without introducing risks to active financial markets. At the same time, the exercise intentionally deferred the broader, more complex work of deploying a full-scale production service, establishing formal institutional responsibilities, and integrating the technology deeply into everyday financial workflows.
The underlying market challenge that inspired the pilot is familiar to institutional participants. Consider a hypothetical tokenized bond whose ownership and secondary trading are represented across several distinct blockchain networks simultaneously. Should the credit assessment of that bond undergo a change, any reliable financial system must be able to accurately identify the relevant instrument and ensure that each destination network receives the appropriate update in a timely manner. Without such synchronized updates, decentralized applications and smart contracts risk acting on fragmented or outdated versions of information concerning the exact same underlying financial obligation.
CCIP Carries Messages as Well as Tokens
At the core of the technical demonstration was Chainlink’s CCIP, an infrastructure framework specifically designed to facilitate the secure transfer of both data and tokens across disparate blockchains. While many early blockchain interoperability solutions focused narrowly on moving cryptocurrency tokens from one network to another, CCIP’s developer toolsets encompass standalone messages as well as complex transactions that seamlessly combine value transfers with explicit programmatic instructions.
The distinction is particularly vital when dealing with analytical financial information, such as a credit rating update. Delivering an updated credit opinion to a digital ledger does not inherently require moving the underlying asset itself. Instead, a recipient application or smart contract can ingest an incoming message and independently decide how to utilize that data in accordance with its own internal rules, governance models, and user permissions.
Furthermore, Chainlink’s documentation for the protocol highlights robust operational features, including message-status tracking, execution verification, and transaction finality tools. These operational details assume paramount importance in institutional financial workflows, where systems must definitively determine whether an update has successfully arrived, whether it has been correctly processed by the receiving ledger, and how automated protocols should handle potential exceptions or network delays.
The broader financial technology sector has paid close attention to these developments. Industry observers and technology reports have frequently examined the configurable security controls and compliance features built into modern interoperability frameworks, noting that institutional adoption heavily depends on robust risk management and verifiable message delivery.
Moody’s Had Already Begun Integrating Ratings Onchain
The recent interoperability pilot does not represent Moody’s first exploration into blockchain-based financial infrastructure; rather, it sits as a calculated continuation within a broader, multi-year technological strategy. Earlier in the year, Moody’s announced a significant integration with Alphaledger on the Solana blockchain, providing digital asset issuers on that high-throughput network with a streamlined option to integrate professional credit ratings directly into tokenized fixed-income products. That development closely followed the initial deployment of Moody’s Token Integration Engine on the Canton network.
Throughout these sequential rollouts, Moody’s has consistently described the TIE architecture as network-agnostic. The overarching strategic aim is to make its established analytical information readily accessible across a wide variety of blockchain environments, ensuring that the underlying credit opinions maintain their traditional credibility and regulatory standing regardless of the underlying technological ledger.
This historical context is essential for understanding the true significance of the recent Chainlink collaboration. Connecting a centralized ratings service to a single distributed ledger and distributing analytical information across multiple, disparate networks simultaneously are closely related but fundamentally distinct engineering tasks. The latest pilot successfully tested a method to significantly extend that informational reach, demonstrating how institutional data can traverse multi-chain landscapes.
Production Success Will Depend on Information Quality
While the completion of the cross-chain pilot provides strong technical evidence that single-route data distribution can function effectively in a controlled test setting, industry analysts note that the ultimate transition to live production environments will encounter much broader challenges. The hardest questions facing tokenized finance extend well beyond the basic engineering capability of successfully carrying a message across a network boundary.
A full-scale production workflow requires rigorous foundational elements. These include standardized instrument identifiers, strict controls governing authorized publishers, immutable records of historical data changes, and clearly defined rules for handling delayed, missing, or disputed information. Without these governance layers, automated financial systems remain vulnerable to systemic operational errors.
Moreover, putting financial data onchain does not alter the fundamental nature of the underlying analytical product. A credit rating is, by definition, an expert analytical opinion regarding credit risk. Integrating that opinion into a blockchain environment does not automatically render an asset risk-free, nor does it eliminate the ongoing necessity for market participants to thoroughly evaluate an instrument’s underlying liquidity, pricing mechanics, and complex legal terms.
Similar asset lifecycle and maintenance themes have emerged in other collaborative demonstrations across the industry, such as those exploring tokenized-equity dividend distributions across multiple enterprise blockchains. These initiatives consistently underscore a central reality of the digital asset era: while a decentralized ledger is exceptionally efficient at carrying and recording an asset, the ongoing obligations, information updates, and analytical maintenance associated with that asset require constant human and institutional oversight.
The recent pilot successfully demonstrates that modern cross-chain infrastructure can effectively route critical financial data in a test environment. However, the ultimate proof of how these technologies will perform for real-world institutional portfolios will depend on the subsequent establishment of named production integrations, formalized update policies, and transparent operating records.