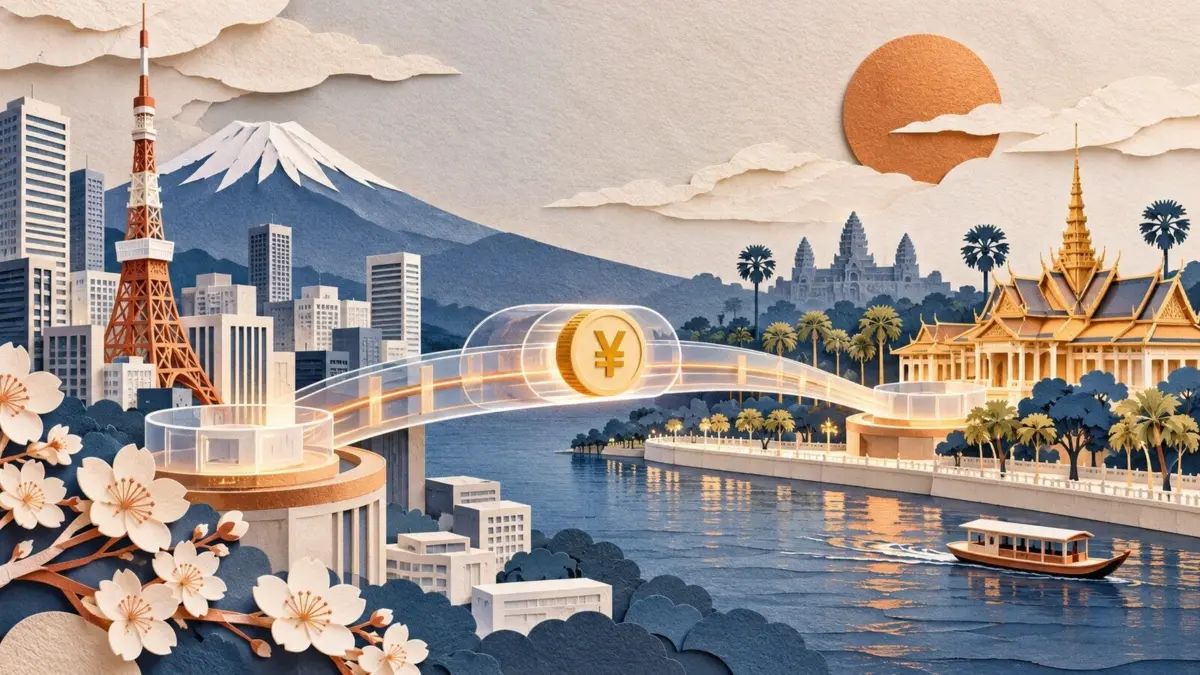
Financial giant SBI Holdings and the National Bank of Cambodia are joining forces to evaluate the potential of a yen-backed stablecoin to streamline and modernize financial transfers between Japan and Cambodia. Rather than requiring everyday consumers to adopt unfamiliar decentralized technologies or manage complex cryptocurrency wallets, the proposed initiative positions the digital asset strictly behind the scenes. The stablecoin is designed to operate exclusively between regulated financial institutions, allowing customers to continue utilizing familiar, traditional channels to send and receive funds across international borders.
This upcoming trial represents a strategic effort to optimize underlying payment infrastructure rather than introducing a retail-facing crypto product. By targeting the wholesale settlement layer, the participating organizations hope to reduce friction, lower operational costs, and accelerate clearing times in the busy remittance corridor connecting the two nations.
The stablecoin sits between the financial institutions
According to the official announcement released by SBI on November 13, the initiative is structured as a closed-loop proof of concept. This controlled trial is designed to thoroughly examine regulatory compliance, technological system integration, and overall commercial viability. Under the framework of the partnership, the SBI group will supply the core banking capabilities, remittance architecture, and underlying token infrastructure. Meanwhile, Cambodia’s central bank will provide crucial regulatory guidance, oversee the framework, and review the ongoing work to ensure alignment with national financial policies.
Importantly, the proposal is intended to complement, rather than replace, Cambodia’s well-established Bakong payment system, which forms the backbone of the country’s domestic digital financial infrastructure.
The distinction regarding customer experience is significant for the success of any cross-border payment innovation. When individuals send money internationally, their primary concerns typically involve transparent fees, competitive exchange rates, and the exact amount available for the recipient to spend. If financial institutions alter their internal settlement methods without disrupting or complicating that front-end experience, the underlying technology can be judged a success only if it visibly improves the complete payment journey from end to end.
However, achieving efficiency is complex. Even if a digital settlement asset allows for significantly faster transfers between two originating and receiving providers, the recipient could still experience delays if local cash-out options, payout availability, or smooth currency conversion services are lacking. Consequently, the evaluation period must carefully assess not only the digital settlement leg of the transaction but also how seamlessly it connects to ordinary, everyday fiat balances on the ground.
JPYSC already has a defined issuing structure
The digital asset at the center of the upcoming trial, known as JPYSC, already possesses a clearly defined institutional issuing structure. An initial launch announcement by SBI in June identified SBI Shinsei Trust Bank as the designated issuer of JPYSC, with SBI VC Trade acting as its primary distributor. During its initial rollout phase, the use of the token was strictly limited to accounts held directly within SBI VC Trade, meaning that external-wallet transfers were unavailable at that stage. Industry observers note that this historical access condition should not be mistaken for proof that every proposed cross-border use case is already operational or open to the public.
This trust-based operational framework distinguishes the token significantly from floating-price cryptocurrencies that trade freely on open markets. The intended reference point for JPYSC is the Japanese yen, while the legal rights, redemption guarantees, and operational routes depend entirely on the issuer and the established service terms. For instance, a customer paying for an expense in Cambodia still faces a currency-conversion question, even if the intermediate settlement asset successfully maintains its stable one-to-one value relative to the yen.
SBI has also explored other potential enterprise applications for the digital asset. Previous reports have highlighted initiatives linking JPYSC with tokenized investment funds in collaboration with global financial institutions like BlackRock. While a common settlement asset can theoretically serve multiple distinct workflows across different sectors of the financial industry, each individual connection requires its own dedicated technical implementation, regulatory approval, and operational permissions.
The bond experiment is a separate project
In addition to the stablecoin remittance trial, SBI disclosed a distinct, separate agreement to test tokenized Cambodian government bonds. This independent experiment is planned to take place on the Canton Network, with the National Bank of Cambodia taking charge of managing comprehensive bondholder information. The initial announcement leaves specific service details, technical integration milestones, and precise timelines subject to further discussions between the involved parties.
Analysts emphasize that these two distinct projects should not be combined into a generalized claim that investors will soon be able to purchase Cambodian government bonds directly using JPYSC. Neither of the official releases establishes such a transaction capability, nor do they outline an active technical bridge connecting the Canton Network infrastructure with Cambodia’s Bakong payment system. Each project serves a completely different function: one examines the mechanics of wholesale remittance settlement, while the other investigates how government-bond holdings and transfers can be accurately represented on a distributed ledger.
The process of tokenizing a bond fundamentally alters its legal representation and transfer mechanism, but it does not remove the issuer’s underlying repayment obligation or eliminate the investor’s need to understand those financial risks. Conversely, a remittance settlement token performs an entirely different operational task. The underlying legal claims associated with these different financial assets remain paramount, even though both leverage blockchain technology to modernize traditional record-keeping.
The relevant measure is what the recipient receives
The formal announcement of the remittance trial schedules interim findings and a live demonstration to take place during the Black Swan Summit. However, the announcement does not establish a definitive commercial launch date, publish a standardized customer tariff schedule, or quantify specific cost savings achieved. Those vital metrics remain questions that can only be answered through empirical evidence gathered during the trial and any subsequent commercial service announcements issued by the partners.
To establish a truly meaningful comparison, the participating organizations will need to evaluate the net amount successfully delivered to the recipient after all fees and currency conversions are accounted for, the total elapsed time until the funds become fully usable, and the resilience of the error-handling process when a payment encounters disruptions. A low blockchain transaction fee in isolation cannot adequately describe or guarantee those broader operational outcomes.
Ultimately, the proposed trial assigns yen stablecoins a very specific operational task: to improve and modernize the settlement arrangements operating quietly behind a defined international payment corridor. The ultimate value of the initiative will depend entirely on whether financial institutions can successfully translate this digital settlement arrangement into a dependable, cost-effective service for the people and businesses that rely on moving money seamlessly between Japan and Cambodia.
Written by the News Desk and edited by Samuel Rae.