
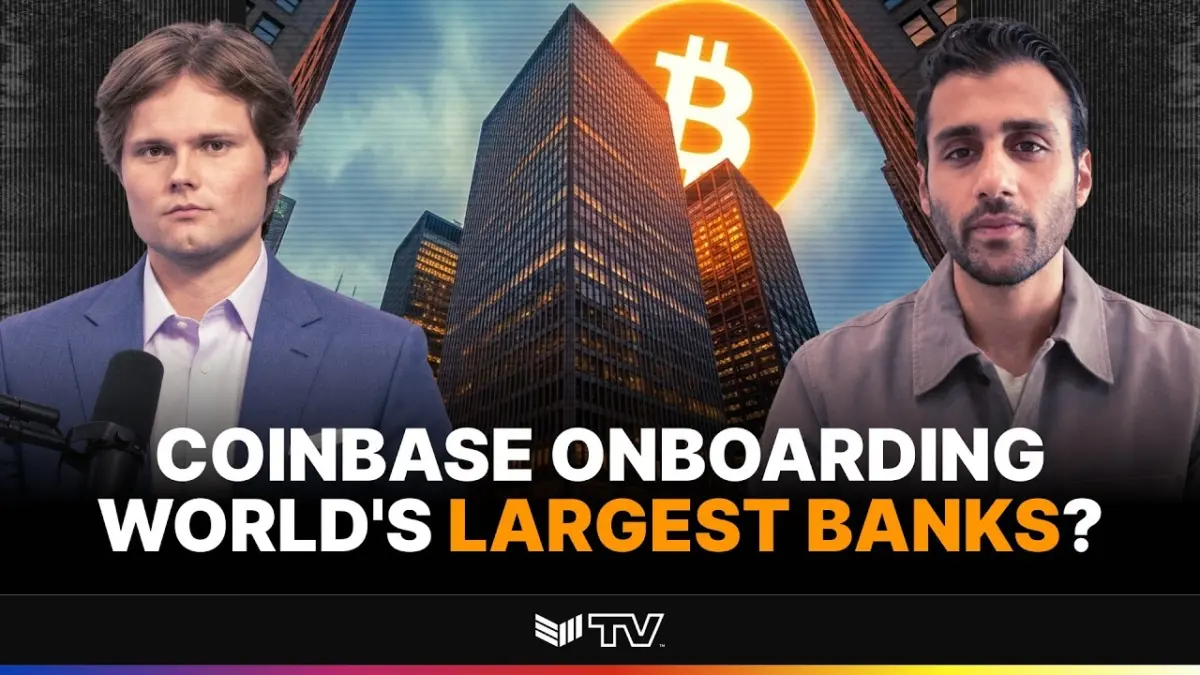
As regulatory frameworks continue to evolve around the digital asset ecosystem, new rules proposed by the Securities and Exchange Commission (SEC) could soon open the door for registered financial advisors to hold Bitcoin directly for their clients. Amid this shifting regulatory landscape, cryptocurrency exchange and infrastructure provider Coinbase is already positioning itself at the very center of the institutional custody story.
Shan Aggarwal, who serves as Coinbase’s first-ever Chief Business Officer, recently shed light on how the platform manages the vast majority of Bitcoin exchange-traded funds (ETFs) and actively supports the broader financial advisor community. According to Aggarwal, the prospective SEC rule changes regarding advisor custody are expected to significantly expand the proverbial pie for Bitcoin access. Rather than competing with traditional wealth management channels, Coinbase aims to serve as the foundational infrastructure provider behind them, bridging the gap between legacy financial planning and digital asset ownership.
The discussion surrounding institutional custody highlights a broader evolution in how major financial institutions view digital assets. Wall Street heavyweights such as BlackRock and JPMorgan are increasingly seeking robust, enterprise-grade Bitcoin infrastructure to service their massive client bases. As traditional finance moves deeper into the digital asset space, infrastructure providers must meet stringent regulatory, security, and operational standards. Coinbase’s ability to anchor major spot Bitcoin ETFs has established its credibility among these institutional giants, proving that digital asset custody can scale to meet the demands of traditional global finance.
This institutional integration is widely viewed as a primary catalyst for the next wave of Bitcoin adoption. While the initial wave of cryptocurrency adoption was largely driven by retail enthusiasts, tech-savvy early adopters, and specialized crypto funds, the next phase is expected to be dominated by mainstream wealth managers, retirement accounts, and traditional institutional portfolios. When financial advisors are legally and operationally empowered to allocate client capital into Bitcoin through familiar custodial frameworks, trillions of dollars in wealth managed by registered investment advisors could gradually flow into the asset class.
Beyond institutional custody and wealth management, Coinbase is actively exploring ways to integrate everyday financial products with cryptocurrency rails. One notable initiative is the Coinbase One Card, a product designed to bridge the gap between traditional spending and digital asset ownership. By offering everyday utility and rewards connected to digital currencies, products of this nature aim to transform casual spenders into active Bitcoin owners, bringing digital assets into daily consumer habits without requiring users to navigate complex exchange interfaces manually.
At the same time, the broader utility of blockchain infrastructure is expanding into high-volume payment rails, most notably through stablecoins. Coinbase views stablecoins not merely as a speculative trading pair, but as a trillion-dollar opportunity to modernize global payments and settlement systems. By partnering with legacy financial institutions like Citi, Coinbase is working to bring stablecoin payment solutions directly to merchants. This collaboration highlights the growing convergence between traditional banking infrastructure and blockchain-based settlement networks, offering businesses faster, cheaper, and more reliable cross-border transaction capabilities.
The evolution of payment systems is also intersecting with technological advancements in other sectors, particularly artificial intelligence. As autonomous software programs and AI agents assume increasingly complex economic roles, questions surrounding how these digital entities will transact value have come to the fore. Industry leaders are actively evaluating whether AI agents will settle transactions using native cryptocurrencies like Bitcoin or rely on stablecoins pegged to fiat currencies. Given the programmatic nature of blockchain networks, digital assets represent the natural medium of exchange for machine-to-machine commerce, potentially opening up entirely new economic paradigms where software applications transact independently on behalf of users.
In addition to institutional custody and enterprise payments, transaction efficiency remains a critical focus for retail and institutional users alike. Solutions like the Bitcoin Lightning Network are playing an increasingly vital role in how Coinbase customers interact with the asset for everyday transactions. By enabling near-instantaneous and low-cost microtransactions, the Lightning Network addresses Bitcoin’s historical scaling challenges, making it viable not just as a long-term store of value, but as a functional medium of exchange for smaller, day-to-day payments.
Coinbase’s expansion strategy also extends into emerging digital asset classes, including collectibles and everyday reward programs. By integrating digital collectibles and consumer-facing incentives into its ecosystem, the company continues to diversify its offerings beyond pure exchange trading fees. These initiatives are designed to foster deeper user engagement, creating a comprehensive financial ecosystem where traditional finance, digital asset custody, merchant payments, and next-generation technologies seamlessly intersect under a unified infrastructure.
Leave a Reply