Published Nov 6, 2026
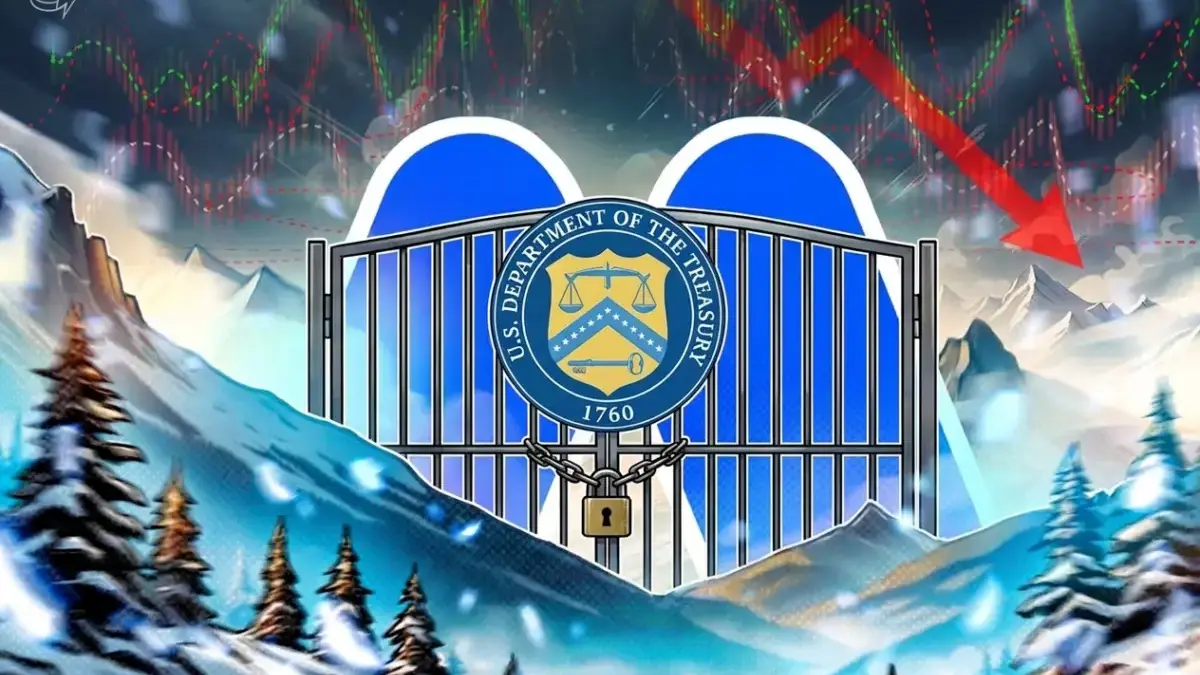
The United States Department of the Treasury took decisive regulatory action on Friday, issuing a formal order to cut cryptocurrency exchange MEXC Global entirely off from the United States financial system. The severe enforcement measure follows sweeping accusations that the major digital asset trading platform facilitated at least $16 billion in transactions tied directly to sanctions evasion, sophisticated cybercrime, and other illicit financial activities over a multi-year period.
The sweeping order was formally handed down by the Treasury’s Financial Crimes Enforcement Network (FinCEN). According to regulatory documents, FinCEN asserted that MEXC knowingly or recklessly handled massive volumes of transactions involving heavily sanctioned groups and state actors located in Iran, Russia, and North Korea. This illicit activity allegedly took place across a five-year window spanning from May 2021 to May 2026. Among these alarming figures, the Treasury’s official press release highlighted approximately $1.5 billion in transactions specifically linked to Russian sanctions evasion efforts amid ongoing geopolitical conflicts.
Under the terms of the newly issued FinCEN order, domestic US financial institutions are strictly prohibited from processing any money transfers or financial interactions involving MEXC Global. To allow institutions adequate time to adjust their compliance parameters and cease operations linked to the exchange, the prohibition is scheduled to take official effect 30 days after its formal publication in the Federal Register.
The severe crackdown underscores a rapidly intensifying regulatory posture by Washington toward offshore cryptocurrency platforms that fail to implement robust anti-money laundering and know-your-customer controls. Treasury officials emphasized that digital asset exchanges serving international clientele must still respect international compliance frameworks, warning that platforms turning a blind eye to illicit capital flows will face the full weight of American financial power.
Addressing the gravity of the enforcement action, United States Secretary of the Treasury Scott Bessent delivered a blunt assessment of the situation, signaling zero tolerance for entities that undermine national security through digital currency networks.
"Financial institutions cannot have it both ways: Either you support the Iranian regime, or you have access to the U.S. financial system," said Secretary Bessent in the Treasury’s official announcement. "Treasury will continue to sever the Iranian regime’s economic lifelines and thwart its desperate attempts to circumvent U.S. sanctions using digital assets."
The regulatory action against MEXC Global does not stand in isolation; rather, it forms a central pillar of Operation Economic Outcast. This broad, multi-agency US Treasury campaign was originally launched in August with the specific strategic objective of systematically dismantling and cutting off financial entities, shell companies, and digital platforms that assist the Iranian government and its proxies in evading international economic sanctions. By targeting the crypto infrastructure allegedly utilized by these networks, Washington aims to close critical loopholes that have historically allowed bad actors to move funds rapidly across borders without traditional banking oversight.
The fallout from the FinCEN order poses significant operational and liquidity questions for MEXC, which has grown to become a prominent venue in the global cryptocurrency trading ecosystem. According to data tracked by analytics platform DefiLlama, the exchange held approximately $4.48 billion in total user assets as of Friday. The sudden barring from the US financial apparatus could trigger heightened withdrawal requests, increased market scrutiny, and potential challenges regarding fiat gateway integrations as international banking partners reassess their risk exposure to the platform.
Following the public release of the Treasury’s order, media outlets sought immediate clarification and response from the exchange’s leadership. Cointelegraph reached out to MEXC Global representatives seeking official comment regarding FinCEN’s allegations, the specific volume metrics cited in the enforcement documents, and the exchange’s planned response to the impending 30-day ban. However, no official statement or reply had been received from the company by the time of publication.
As the 30-day countdown to the formal implementation of the FinCEN order begins, market participants, legal experts, and compliance officers are closely monitoring the situation. The development serves as another stark reminder of the escalating risks facing centralized cryptocurrency exchanges operating across multiple international jurisdictions while grappling with strict Western regulatory enforcement.